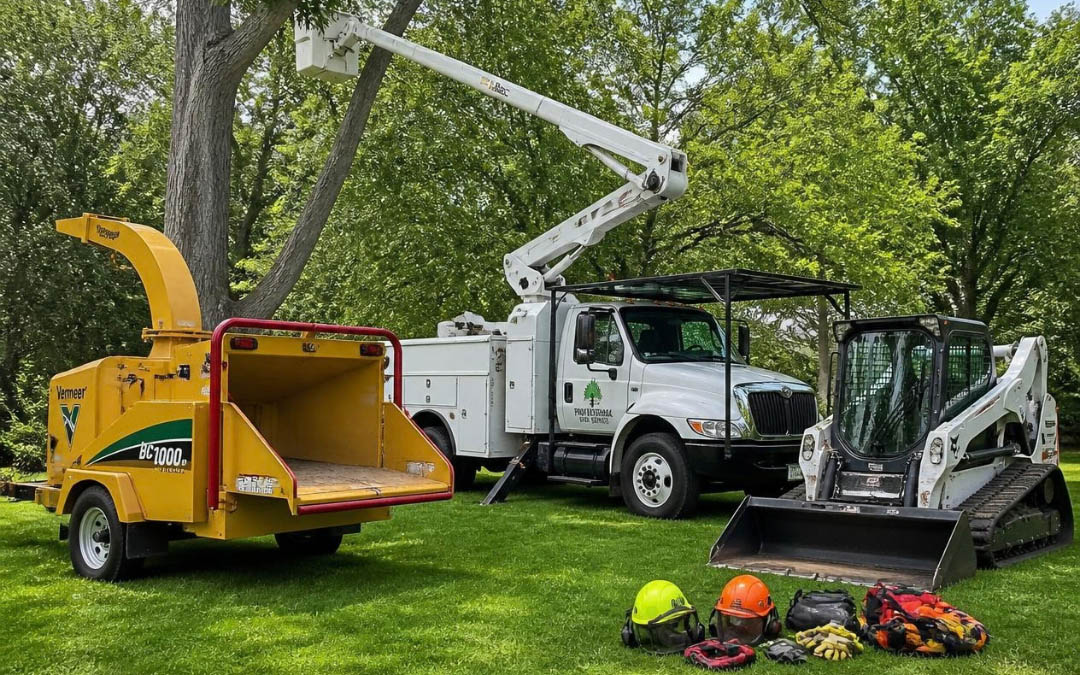
Your equipment is the engine of your business. Between woodchippers, stump grinders, skid steers, loaders, chainsaws, and specialized rigging gear, a tree care operation can easily haul hundreds of thousands of dollars in machinery on a single trailer.
When a critical piece of equipment is stolen from a job site or damaged in transit, the financial loss goes beyond the cost of repairs. Without functional machinery, your crew cannot complete jobs, leading to costly operational downtime.
This raises a crucial question for arborists and tree service owners across Southwest Michigan: Is all of your equipment listed and covered properly on your commercial policy?
Step 1: Build an Accurate Equipment Inventory
A thorough policy review begins with a clear inventory. Tree service business owners in Dowagiac and surrounding areas should maintain a current record of all operational assets, including:
-
- Year, make, and model
- Serial numbers / VINs
- Purchase price and current estimated market value
- Specialized attachments (grapples, buckets, winches)
Did you purchase another chipper this season? Did you add a stump grinder, upgrade a loader, or buy high-value climbing gear?
If your insurance representative does not have a record of a newly acquired asset, that machinery may be omitted from your policy schedules.
Step 2: Commercial Property vs. Inland Marine Coverage
Standard commercial property insurance primarily addresses assets kept at a fixed physical location, such as your shop or yard.
Tree service machinery, however, is constantly on the move. Your gear travels from your shop in Dowagiac to residential or commercial job sites throughout Cass County, Berrien County, and Van Buren County. It may sit on a trailer overnight or move between multiple work locations during the day.
Because mobile machinery faces different hazards than fixed property, Inland Marine Insurance (often referred to as Contractors Equipment Coverage) is specifically structured to address mobile equipment, tools, and machinery while in transit or on active job sites.
Step 3: Towing vs. Physical Damage (Commercial Auto Misconceptions)
A common point of confusion involves towed machinery. Many business owners assume that because a woodchipper or stump grinder is hitched to an insured work truck, the truck’s Commercial Auto policy automatically covers damage to or theft of the towed unit.
In reality, Commercial Auto Insurance and Contractors Equipment Coverage serve distinct purposes:
-
- Commercial Auto Insurance generally addresses liability and physical damage related to the motor vehicle itself.
- Trailers, Chippers, and Mobile Machinery often require separate scheduled coverage or specific endorsements to address theft, rollover, or accidental physical damage.
Reviewing your trucks, trailers, and heavy equipment together clarifies which specific policy applies to each asset.
Critical Questions to Review on Your Current Policy
When assessing your machinery and tool coverage, review the following details within your policy documents:
-
- Scheduled vs. Unscheduled: Is high-value machinery specifically listed on an equipment schedule?
- Valuation Method: Is coverage structured around Replacement Cost or Actual Cash Value (ACV)?
- Deductible Structure: What deductible applies to total losses versus partial equipment damage?
- Theft Exclusions: Are there specific lock or security requirements for equipment left on job sites or open trailers overnight?
- Transit Coverage: Are items covered while actively being transported on local roads and highways?
- Rented or Borrowed Gear: How does your policy respond if you rent a specialized boom truck or loader for a large job?
- Accessories & Attachments: Are expensive add-ons (like specialized grapple buckets or remote controls) included in the total value?
Policy forms, terms, conditions, and exclusions vary significantly. Reviewing the specific policy provisions helps avoid unexpected gaps during a claim.
Keep Your Policy Up to Date
As tree companies grow, they acquire, upgrade, or trade in equipment to handle larger contracts. Insurance updates should occur alongside these business purchases.
Make it a standard operational process to inform your insurance representative whenever you buy, sell, lease, or retire major machinery.
Commercial Insurance for Tree Care Professionals in Dowagiac, MI
Tree Trimmers Insurance Agency, a division of John Scott Insurance, works directly with tree care, arborist, and land-clearing operations in Dowagiac, Cassopolis, Niles, Benton Harbor, St. Joseph, and across Southwest Michigan.
We focus on the unique operational hazards of the tree care industry. Contact Tree Trimmers Insurance Agency today to schedule an equipment inventory and commercial policy review for your business.