As summer transitions into fall across Michigan, weather patterns bring high-wind events, severe thunderstorms, and early lake-effect ice events. For arborist businesses operating throughout the state, autumn triggers a surge in high-demand, emergency storm response jobs. At Tree Trimmers Insurance, a division of John Scott Insurance, our agents specialize in helping commercial tree care contractors structure their policies to navigate these high-hazard seasonal workloads effectively.
While rapid-response work increases revenue, operating in high-wind conditions near unstable structures and downed power lines introduces severe operational exposures. Understanding how emergency operations affect your Workers’ Compensation Experience Modification Rating (EMR) and General Liability policy structures helps maintain predictable insurance overhead.
Direct Answer: How Emergency Storm Work Drives Insurance Costs
Emergency tree work increases insurance costs primarily through two mechanisms:
- Workers’ Compensation EMR Escalation: Claims resulting from high-severity incidents (e.g., rope failures, chain saw kickbacks, or electrocutions) increase your Mod Factor for three policy years, directly multiplying your base Workers' Comp rate.
- General Liability Classification & Payroll Audits: Unplanned overtime and unclassified subcontractor labor during emergency callouts can result in unexpected premium adjustments during annual policy audits.
3 Critical Operational Exposures During Michigan Fall Storm Cleanup
High-Hazard Work Environment & EMR Impact
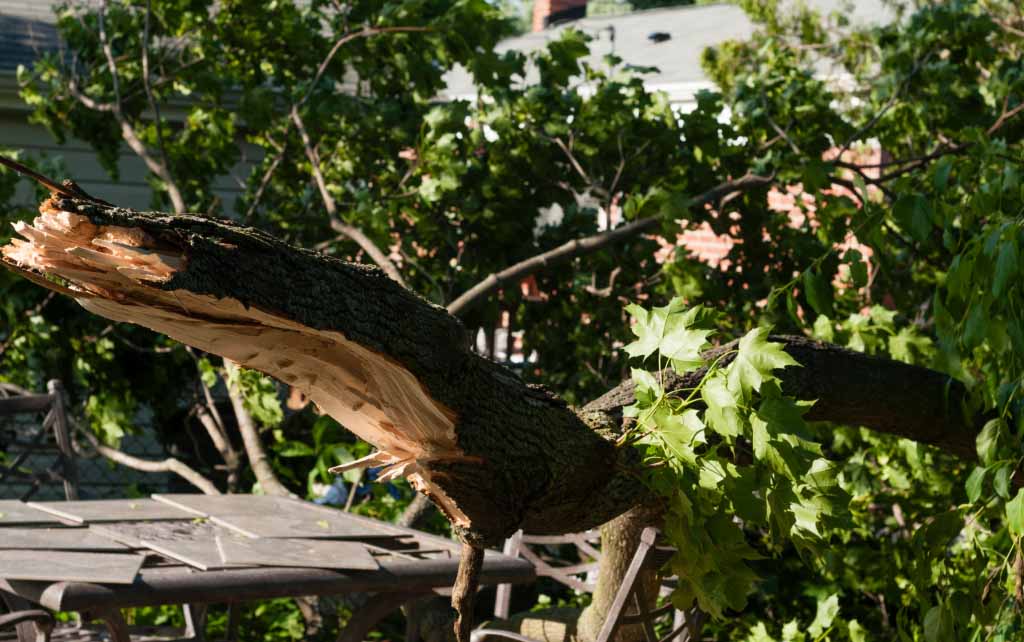
Emergency storm jobs present immediate hazards: suspended limbs under tension (springpoles), compromised root systems, and obscured electrical lines.
- The Exposure: A single catastrophic Workers' Comp claim can raise an EMR above 1.0. A higher EMR increases annual premiums across your entire payroll—not just for the crew involved in the incident.
- Risk Control Strategy: Conduct documented Job Site Hazard Analyses (JSHA) prior to engaging equipment on storm sites. Maintain strict adherence to ANSI Z133 safety standards, specifically regarding electrical hazards and drop-zone management.
Subcontractor Liability & COI Verification
During widespread storm events, arborist contractors frequently scale capacity by bringing on 1099 subcontractors or independent crane operators.
- The Exposure: If a subcontractor causes third-party property damage or suffers an injury without holding their own active General Liability and Workers' Comp policies, the primary contractor’s policy may absorb the loss. Furthermore, unverified subcontractor payments are typically reclassified as employee payroll during an annual audit, generating additional premium charges.
- Risk Control Strategy: Collect an updated Certificate of Insurance (COI) directly from the subcontractor's agent prior to work initiation. The team at Tree Trimmers Insurance, a division of John Scott Insurance, assists contractors in reviewing subcontractor certificates to ensure proper policy limits, endorsements, and active coverage are in place before crews deploy.
Commercial Auto and Fleet Operations in Adverse Weather
Transit to and from emergency sites during high-wind or low-visibility conditions increases collision frequency.
- The Exposure: Vehicle accidents involving heavy chip trucks, trailers, or bucket trucks carry high severity, potentially exhausting primary Commercial Auto policy limits.
- Risk Control Strategy: Enforce driver qualification standards, conduct pre-trip vehicle inspections, and maintain a Commercial Umbrella policy to provide secondary coverage limits above underlying Commercial Auto and General Liability policies.
Standard Coverage Checklist for Tree Trimmer Contractors
| Coverage Type | Primary Function in Emergency Response | Key Policy Consideration |
| General Liability | Covers third-party property damage and bodily injury caused by operations. | Verify tree trimming and removal class codes match actual scope of work. |
| Workers' Compensation | Covers employee medical costs and lost wages for job-related injuries. | EMR rating directly impacts annual costs; safety programs help manage Mod scores. |
| Commercial Auto | Protects work vehicles, bucket trucks, and trailers in transit. | Includes liability for vehicle collisions and physical damage options for business vehicles. |
| Tree Trimmer Equipment | Covers mobile equipment (chippers, stump grinders, saws) against theft or damage. | Covers tools away from the main shop location and on active job sites. |
| Commercial Umbrella | Provides higher liability limits above underlying Auto, Liability, and Employer's Liability. | Helps absorb large claims that exceed primary policy limits. |
Frequently Asked Questions
How does an annual Workers' Comp audit handle emergency overtime pay?
In Michigan, Workers' Compensation payroll calculations typically allow the overtime premium portion (the "time-and-a-half" fraction) to be excluded from audited payroll, provided your payroll records clearly differentiate regular pay hours from overtime pay hours.
Does General Liability cover damage to a customer's home caused by a falling branch during removal?
Standard General Liability policies for tree trimmers generally cover accidental third-party property damage resulting from operations, subject to policy terms, exclusions, and deductibles. Proper classification of tree removal vs. standard trimming on your policy is required.
What coverage is required when borrowing or renting specialized storm response equipment?
Rented or borrowed machinery (such as specialized cranes or large wood chippers) typically requires Inland Marine / Rented Equipment coverage. Standard General Liability does not cover damage to equipment you rent or borrow.
Get a Coverage Review Before Storm Season Begins
Navigating fall storm surges requires an insurance strategy tailored specifically to the tree care industry. Whether you need to verify that your current General Liability codes match your actual job operations, add rented equipment coverage, or ensure your Commercial Auto limits are structured correctly for emergency dispatch, working with specialized arborist agents makes all the difference. Contact Tree Trimmers Insurance, a division of John Scott Insurance, at (877) 810-8872 or request a free quote online to evaluate your policy limits and protect your business heading into this season.